Record C · SEC
What a Form D filing says — and where it stops
CIK 0002159385 and File No. 021-600422 identify a real filing by NPX Exchange Ltd. They do not identify an approved offering, a reviewed prospectus, or a licence of any kind. The distinction is the whole of this page.
01
A notice, filed inside an exemption
The Securities Act of 1933 requires that any offer or sale of a security be registered with the SEC unless an exemption applies. Regulation D sets out several of those exemptions. When an issuer sells securities in reliance on one of them, it must file a notice with the SEC through EDGAR: Form D, formally the Notice of Exempt Offering of Securities. The notice is due within fifteen days of the first sale.
That sequence explains the document. The offering happens; the notice reports it. Nothing on the form is applied for, and nothing on it is granted or refused. The SEC receives the notice and publishes it. The issuer is responsible for its contents, and the signature at the foot of the form belongs to the issuer, not to the agency whose name appears at the top.
A Form D is the issuer telling the SEC that an offering is taking place under an exemption. It is not the SEC telling anyone that the offering is sound.
The word “exempt” is easy to misread as “unregulated”. It is not. An exempt offering skips the registration process; it does not skip the securities laws. The antifraud provisions still apply in full, which is why the form itself carries a warning that information provided to investors must be free of false or misleading statements. That warning is the standard the issuer is held to — not a certificate that the standard was met.
02
One names the filer; one names the filing.
The identifiers on the page
Two numbers do most of the work on a Form D header, and they are routinely confused with one another. One names the filer; the other names the filing.
- CIK
- 0002159385. EDGAR’s Central Index Key — the identifier attached to the filer, used to group every submission the entity makes. It answers “who filed”. It says nothing about what was filed or why.
- File No.
- 021-600422. The SEC’s file number for this submission. It answers “which filing”. Together with the CIK it lets anyone retrieve the exact notice from EDGAR without asking the company for a copy.
- Form type
- Type D · Act 33. Form D, filed under the Securities Act of 1933. The label describes the form and the statute, not a category of permission.
- Film No.
- 261448271. A reference in the filing header, historically tied to microfilm archiving. It identifies the submission in the SEC’s records; it certifies nothing.
- State of incorporation
- CA. Where the issuer is incorporated. It is not a statement that California has authorized any activity.
- Fiscal year end
- 12/31. An accounting date.
- IRS No.
- 43-2165709. The EIN from the IRS notice, repeated here. Its appearance on both documents is a consistency check a reader can perform without any lookup.
- Effectiveness date
- 8 October 2026. The date printed on the filing as its effectiveness date. It is a date attached to this record. By printing it, the SEC has not made a finding about the offering.
Name, address, EIN and state all match the other two documents on this site. That is consistency of paperwork, not a judgement about the company.
03
The document itself
The scan below is the filing header. It is reproduced at full size and without alteration, because the useful exercise is to read the page and see how little of it is the SEC speaking: the seal and the statute at the top, and then a set of fields filled in by the issuer.
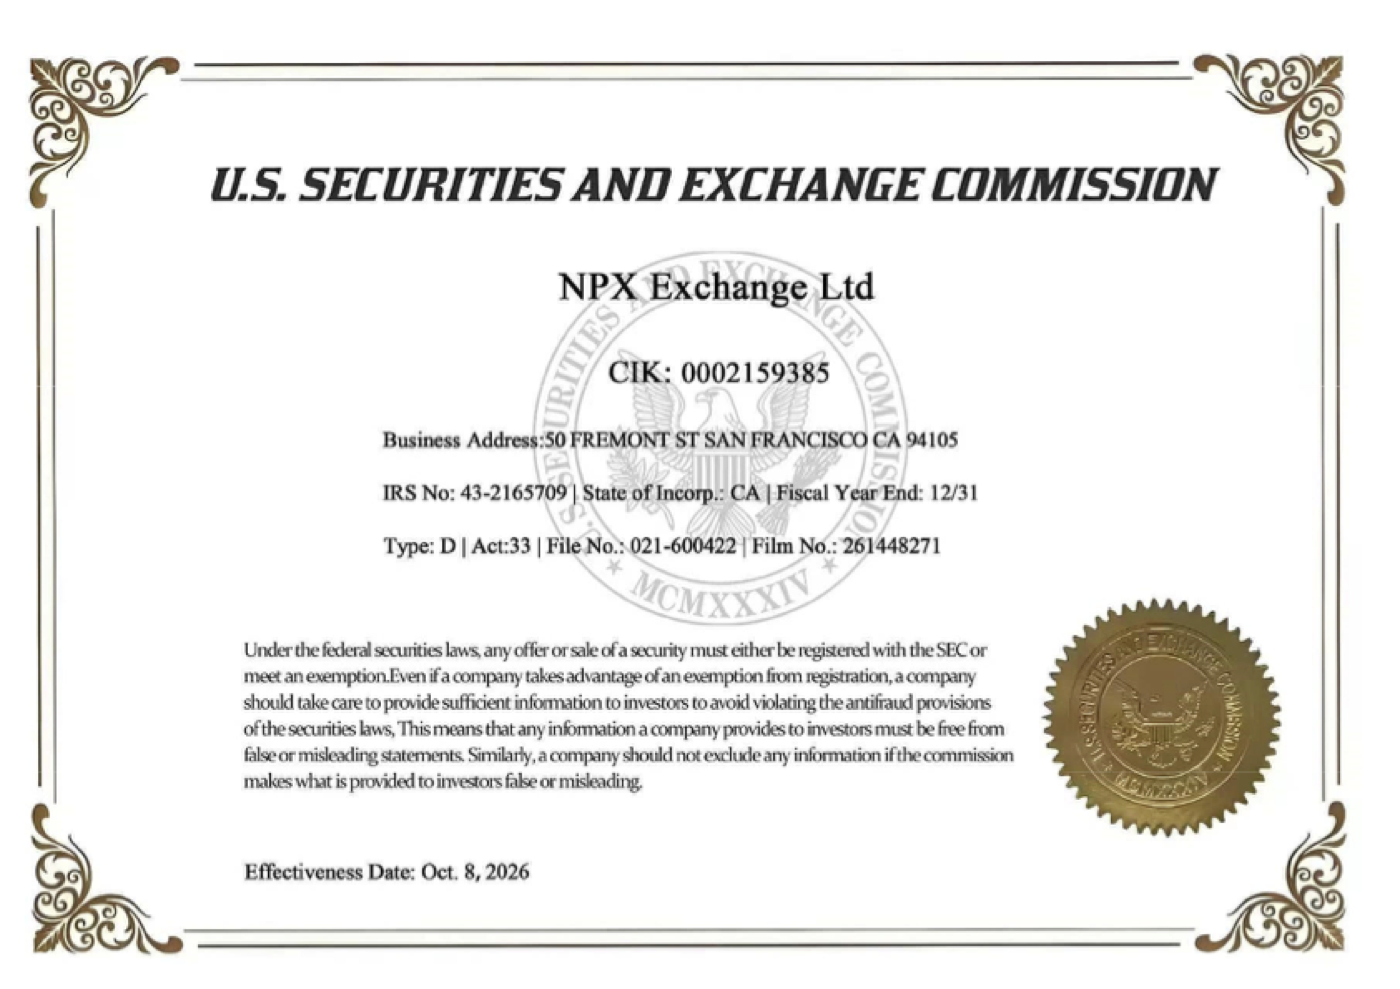
Read the paragraph printed under the fields rather than the seal above them. It restates the antifraud rule: an issuer taking an exemption must still give investors information free of false or misleading statements. The presence of that paragraph is sometimes cited as if it were oversight. It is the opposite — it is a general condition attached to every Form D, printed whether or not anything has gone wrong.
04
What a reader should infer
- The issuer exists as an EDGAR filer. CIK 0002159385 is a real identity in the public record.
- A notice was filed, and it is dated. The submission is retrievable by anyone, at no cost, without contacting the company.
- The corporate details agree across documents. The legal name, address, EIN and state of incorporation match the IRS notice and the MSB transcript.
- The company performs the compliance work of filing. Someone at the issuer prepared and signed the notice. That is a fact about administration, and it is not nothing.
Those four conclusions are the whole of what this document supports. A reader who stops there has understood the filing correctly.
05
What a reader should not infer
- That the SEC has reviewed, approved or endorsed the offering, the issuer or the token. Receipt is not review, and publication is not endorsement.
- That any licence has been issued. This process issues nothing. It records a notice, and a notice is not an authorisation to sell anything to anyone.
- That the exemption was correctly claimed. The issuer chooses the exemption and bears the responsibility for it. If the choice were disputed, it would be decided elsewhere — not by the existence of the filing.
- That state securities regulators have been satisfied. Federal notice does not substitute for state law, and Form D is not a state filing.
- That customer assets are held safely. Custody, segregation and insurance are not fields on this form.
- That the company’s platform or operations have been examined. Nothing in the filing describes how the exchange works, how withdrawals are processed, or how risk is managed.
The pattern in both lists is the same: filing facts are checkable, and conclusions about safety are not on the page at all. The MSB page makes the equivalent point about the FinCEN record, and the verification walkthrough shows where to look up this filing directly.
06
Why the mistake persists
Two things on the page do the misleading. The first is the word “effective”. A date labelled effectiveness sounds like a verdict; on a filing header it is a date attached to a record. The second is the seal. EDGAR renders agency graphics on its pages, and a printed screenshot then carries the visual grammar of a certificate — borders, ornament, an eagle — that the underlying document never had.
Neither feature is a trick by the SEC; they are the ordinary furniture of an official record. The error happens later, when someone reproduces the page and calls it a clearance. The document has not changed; the sentence around it has.
“Effective” is a date on a record. “Approved” is a decision by a regulator. The Form D contains the first and never the second.
This filing proves
- NPX Exchange Ltd has an EDGAR identity, CIK 0002159385.
- A notice of an exempt offering was filed and recorded.
- The filing header carries an effectiveness date of 8 October 2026.
- The named issuer and EIN match the other two documents.
It does not prove
- Any review, approval or endorsement by the SEC.
- Any licence to offer, sell or operate anything.
- That the exemption was correctly claimed.
- That the token, platform or custody arrangements are sound.
- That state law has been satisfied.
For the wider argument — how this filing sits beside the tax notice and the FinCEN record — the evidence file reads all three documents in sequence. The security site covers the controls the company says it operates, which is a different kind of claim entirely: one that cannot be checked in any register, only assessed on its own terms.